
Why won’t anyone insure my coastal home?
Someone will. If you own a house near the water on the South Shore — Hull, Scituate, Cohasset, Hingham harbor, Humarock, Marshfield — you’ve probably heard “we don’t write that close to the coast” from at least one company. Here’s what’s going on, and what to do about it. We’ve placed coastal homes from our Hingham office since 1979.
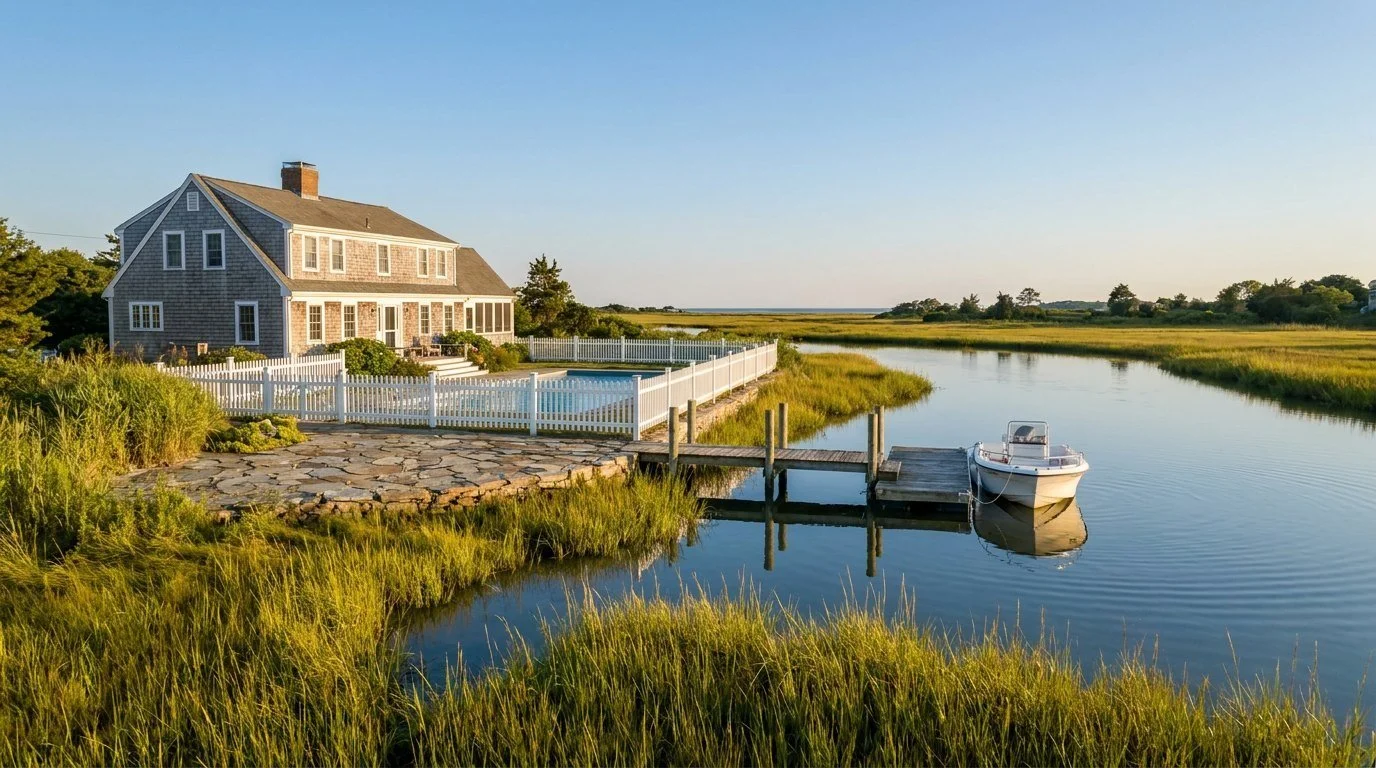
Why companies say no
One big storm. A nor’easter or hurricane can damage hundreds of houses on the same day. So many standard companies:
- Limit how many homes they insure near the ocean, or
- Draw a line a certain distance from the water and stop there.
It isn’t about you or your house. It’s about how many houses they already insure on your stretch of coast.
What they’ll ask you
How far from the water
Measured in feet, sometimes in miles. Each company draws its line in a different place, so a house one company won’t touch is an ordinary risk to another. We know where each company’s line is. That’s the main reason an independent agent helps here.
The roof
Age and condition matter most. An old roof is the most common reason a coastal application is turned down. A new roof is the single change most likely to open doors.
Wind and hurricane deductibles
Most coastal policies have a separate deductible for wind or named-storm damage. It’s often a percentage of your home’s insured amount, not a flat dollar figure. On a house insured for several hundred thousand dollars, that’s real money. We show you the number in dollars before you buy, not after a storm.
Flood is a separate policy
Homeowners insurance doesn’t cover flooding from the ocean, a storm surge or a river. That needs a separate flood policy, usually through the National Flood Insurance Program. If you have a mortgage on a house in a mapped flood zone, your lender will require one. We write flood insurance and can tell you whether your address needs it.
Construction and age
Older shore houses raise questions a website quote never asks:
- A cottage that became a year-round home
- Knob-and-tube wiring
- An oil tank
- A foundation that’s really posts
Answer them once with us. We carry your answers to every company we approach.
What we do
- We shop for you. We write coastal homes with many insurance companies, and they don’t all say no. We go to the ones that write on your part of the coast and bring you the choices.
- We know the FAIR Plan. If a house doesn’t fit any of them, there’s the Massachusetts FAIR Plan, which exists for exactly this. We’ll tell you plainly whether it’s the right fit or just the only option this year.
- We check again at renewal. A new roof, or a change in what a company is willing to write, can move you back to a standard company.
What to have ready
- The year the roof was replaced
- The year the house was built, and any major renovation
- The heating (gas, oil or electric) and roughly how old it is
- The distance to the water, if you know it
- Your current policy’s declarations page
That’s enough for us to start.
Where we do this most
Hull, Scituate, Cohasset, Hingham, Weymouth, Marshfield and Duxbury.
Ask us about your coastal home · Already a client? Request a certificate or proof of insurance.
Talk to us.
781-749-8386 LawlessAgency@Gmail.comVisit
13 Whiting Street
Hingham, MA 02043
Monday to Friday, 9 am to 3 pm
Visits by appointment
Do you have enough coverage?
Ask yourself: if your insurance company issued a check for the coverage amount on your policy, would it be enough to rebuild your home and protect everything you’ve worked for?
- Check local construction costs. Materials and labor change over time. Make sure your coverage would fully rebuild your home today.
- Don’t forget flood coverage. Standard homeowners policies don’t cover floods, and flooding can happen outside flood zones too.
- Protect beyond the basics. An umbrella policy adds protection when a lawsuit or claim goes past your home or auto limits.
- Review and update when needed. Your policy should reflect your needs. If your limits are too low, we’ll help you explore your options.
We cannot make changes to your policy without your express consent.